Two of the most common funding products business owners ask about are the term loan and the line of credit. They sound similar because both provide access to capital, but they work in fundamentally different ways and serve different needs. Choosing the wrong one can mean paying for capital you do not use, or struggling with a payment structure that does not match your cash flow. In this guide, Ashley Boswell and Damon Boswell break down the differences between a business term loan and a business line of credit, and explain how to choose the one that fits your business.
At ASAP Capital Solutions, we help owners compare these options every day. Damon Boswell often explains that the choice comes down to how you plan to use the funds and how predictable your needs are. A term loan is built for a specific, planned investment. A line of credit is built for flexibility and ongoing access. Ashley Boswell adds that understanding this distinction is the single most important step in choosing between the two.
What Is a Business Term Loan?
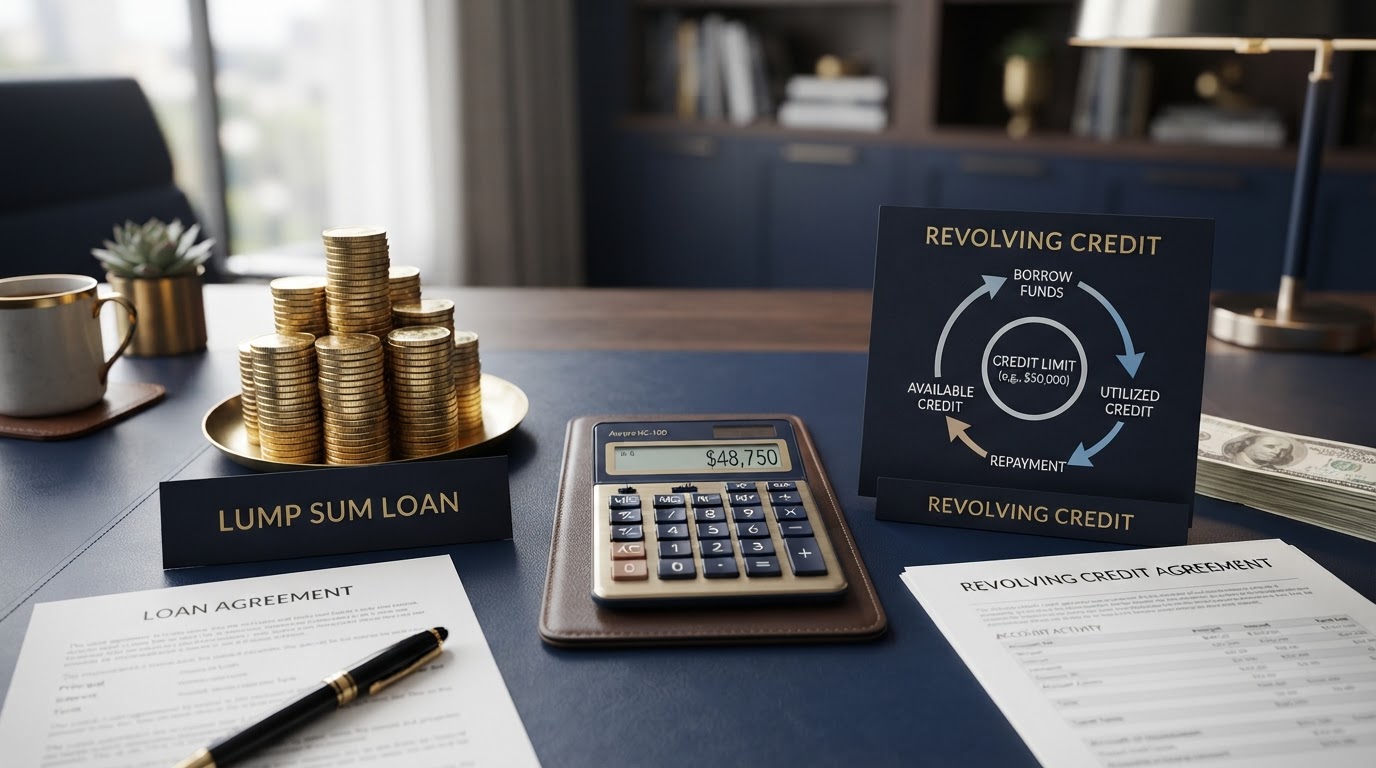
A business term loan is a funding product in which a lender provides a business with a lump sum of capital that is repaid over a set period, typically with interest, according to a fixed repayment schedule. The business receives the full amount up front and repays it in regular installments, usually monthly, over a term that can range from a few months to ten years or more depending on the product and lender.
Ashley Boswell explains that the defining feature of a term loan is predictability. You know how much you receive, you know your payment amount, and you know when the loan will be paid off. Interest accrues on the entire loan amount from the start, regardless of when you use the funds. Damon Boswell adds that this predictability makes term loans well suited for planned investments such as equipment purchases, expansions, or large one-time expenses where you can map the return against the repayment schedule.
What Is a Business Line of Credit?
A business line of credit is a revolving credit facility that gives a business access to funds up to an approved credit limit. It functions similarly to a business credit card in that you can draw funds, repay them, and draw again as long as the account remains in good standing. The key difference is that a line of credit often provides higher limits and may offer lower costs than a credit card, depending on the lender and terms.
Damon Boswell notes that with a line of credit, interest accrues only on the amount you actually draw, not the full approved limit. If you have a $50,000 limit but use only $10,000, you are charged interest only on that $10,000. As you repay what you have drawn, that portion of your limit becomes available again, which is why it is called revolving credit. Ashley Boswell adds that this structure can make a line of credit more cost-efficient than a term loan when your needs are intermittent or unpredictable.
Pro tip from Damon Boswell: A line of credit is a tool for managing timing, not for solving structural problems. If your business is profitable but occasionally cash-strapped because of when money comes in versus when it goes out, a line of credit can smooth those gaps.
The Key Differences at a Glance
Based on current market standards, the differences between a term loan and a line of credit come down to structure, cost, and flexibility. A term loan provides a single lump sum with a fixed repayment schedule and interest charged on the entire amount. A line of credit provides revolving access up to a limit with interest charged only on what you draw. Term loans typically offer higher amounts and longer terms, while lines of credit offer more flexibility but may have shorter terms and higher rates.
Ashley Boswell walks through the repayment difference. A term loan requires the same payment every month whether you had a record month or a slow one. A line of credit requires payments that start when you draw and are based on the amount you have used. Damon Boswell adds that term loans require little maintenance after approval, while lines of credit may require ongoing account reviews, annual renewals, and fees if the line is unused for too long.
How Interest Is Charged
The way interest accrues is one of the most important differences. With a term loan, interest accrues on the entire loan amount from day one. A $50,000 loan at 8% interest means you are paying interest on the full $50,000 from the moment the loan is funded, regardless of when you actually spend the money. With a line of credit, interest accrues only on the amount you have drawn. If you have a $50,000 limit but use only $5,000, you are charged interest only on that $5,000.
Damon Boswell notes that term loan rates are often lower than line of credit rates, because the lender has more certainty about the amount and the term. Lines of credit typically carry higher rates because the lender must keep capital available without knowing exactly when or how much you will draw. Ashley Boswell adds that this is why the right choice depends on your use case. If you need the full amount immediately, a term loan's lower rate may win. If you need intermittent access, a line of credit's pay-only-for-what-you-use structure may save you money overall.
Key takeaway from Ashley Boswell: Do not compare a term loan rate to a line of credit rate in isolation. Compare the total cost based on how you will actually use the funds. A higher rate on a smaller drawn balance can cost less than a lower rate on a full lump sum you did not need all at once.
When a Term Loan Tends To Be the Better Fit
A term loan is usually the better choice when you have a specific, planned use for a known amount of capital. This includes purchasing equipment or machinery, expanding to a new location, acquiring another business, refinancing existing debt at better terms, purchasing inventory in bulk, or funding a large marketing or growth campaign with a clear timeline.
Damon Boswell notes that the best use of a term loan is one where the return is clear and the repayment timeline aligns with the benefit. If you are buying equipment that increases capacity for years, a longer-term loan makes sense. Ashley Boswell adds that term loans are also a good fit when you want the predictability of a fixed payment for budgeting purposes, because you know exactly what your obligation will be each month for the life of the loan.
When a Line of Credit Tends To Be the Better Fit
A line of credit is usually the better choice when your needs are variable, intermittent, or unpredictable. This includes bridging cash flow gaps while waiting on customer payments, purchasing seasonal inventory before peak demand, covering payroll during slow periods, handling unexpected expenses, taking advantage of supplier discounts for bulk purchases, and keeping a safety net available without paying for capital you do not need yet.
Ashley Boswell notes that because you only pay for what you use, a line of credit can be an efficient way to keep capital available without the cost of a full lump sum. Damon Boswell adds that disciplined owners often keep a line of credit in reserve, drawing only when a clear return or a genuine need justifies it. The flexibility is the core advantage, but it requires discipline to avoid drawing without a plan.
Qualification Requirements
While every lender sets its own standards, the factors that influence eligibility for both products are fairly consistent. Lenders commonly review personal credit score, with traditional banks often preferring 680 or higher while online and alternative lenders may consider scores starting around 600. Time in business is another major factor, with banks frequently preferring 2 years or more while alternative lenders may work with 6 to 12 months. Annual revenue also plays a critical role, with banks often looking for $100,000 or more.
Damon Boswell points out that lines of credit may have slightly more flexible requirements than term loans at some lenders, because the lender is not committing the full amount up front. However, this is not a guarantee. Ashley Boswell adds that for both products, strong, consistent monthly deposits are one of the most persuasive signals a business can show a lender, because they demonstrate the cash flow needed to service the debt.
How to Decide Between a Term Loan and a Line of Credit
Start by mapping out your needs. Do you have a specific, one-time expense with a known amount? Or do you have ongoing, intermittent needs that vary in size and timing? If your answer points to a single planned investment, a term loan may be the better fit. If your answer points to flexible, recurring access to capital, a line of credit may be the better fit.
Damon Boswell suggests owners ask themselves whether they need all the money at once. If you need the full amount immediately for a specific purchase, a term loan's lower rate and fixed schedule may win. If you need access to capital but are not sure exactly when or how much you will use, a line of credit's flexibility may save you money. Ashley Boswell adds that some businesses benefit from both: a term loan for a major investment and a line of credit for ongoing working capital.
How This Connects to Your Funding Options
A term loan and a line of credit are two of several funding paths a business can explore through ASAP Capital Solutions. Others may include a merchant cash advance, invoice factoring, a secured business loan, or a credit-based strategy like 0% credit card stacking for qualified applicants. None of these options are guaranteed, and all are subject to review, underwriting, documentation, credit profile, business revenue, and funding partner requirements. The right path depends on your revenue, your timeline, your credit profile, and how you plan to use the funds.
If you are not sure which option fits your business, the fastest place to start is the AI Funding Match Calculator. It takes under 60 seconds, and a funding specialist can review your profile and follow up by phone during your preferred call window. As Ashley Boswell and Damon Boswell always remind owners, the businesses that get the best results are the ones that understand their options, match the structure of the funding to the nature of their need, and never pay for capital they do not actually use.